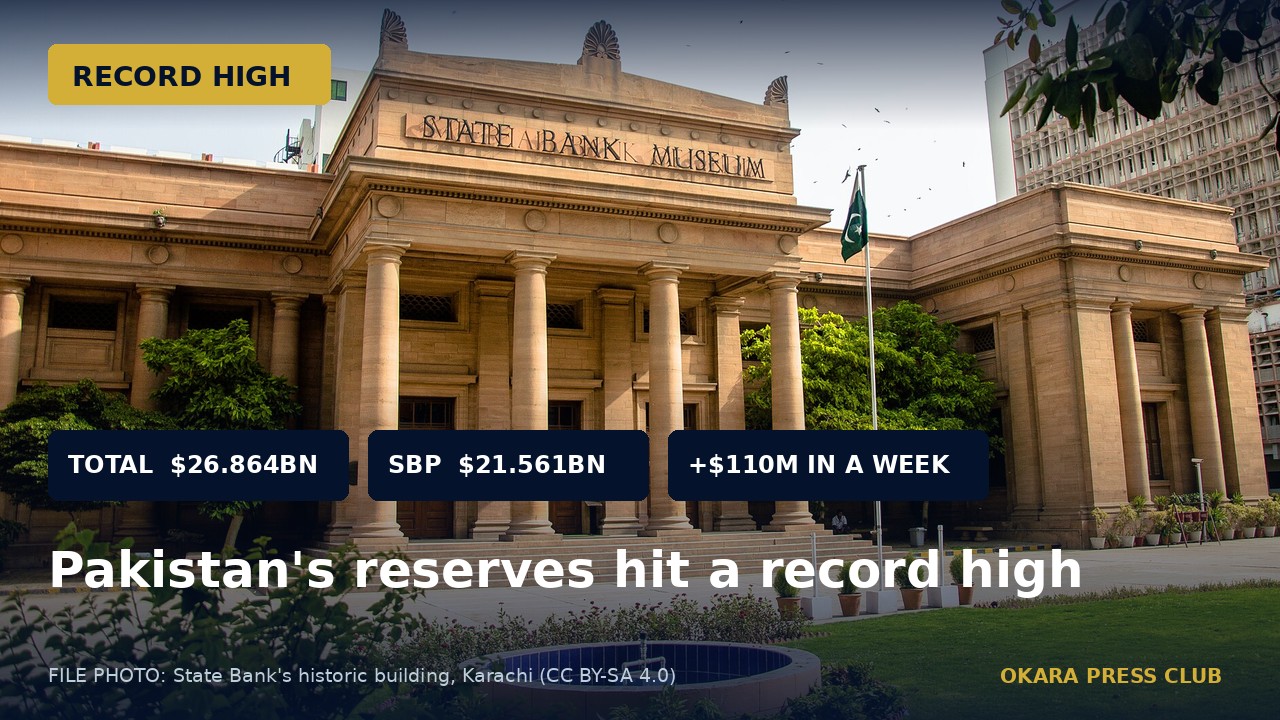
Pakistan’s foreign exchange reserves have climbed to a record high of $26.864 billion, the State Bank of Pakistan (SBP) reported on Thursday, as the central bank’s holdings continued to build despite pressure from the war in the Gulf.
Total liquid reserves stood at $26.864 billion on 30 October, up $110 million from $26.754 billion a week earlier. Reserves held by the central bank rose by $39 million to $21.561 billion, while commercial banks held $5.303 billion, up $71 million over the week.
The State Bank’s reserves stood at $16.568 billion in February, meaning the central bank has added more than $5 billion since then. The improvement has come even as the conflict in the Gulf, which began in late February, pushed up oil prices and unsettled weaker economies across the region.
The financial sector regards the current level of reserves as enough to keep the exchange rate steady and to encourage exporters to bring their earnings home promptly. A stable currency also gives importers greater confidence when placing orders.
Currency experts, however, believe the rupee is overvalued, which makes dollars cheaper for importers and helps explain why the trade deficit keeps widening. The deficit reached $14.6 billion in the first four months of the current fiscal year, with imports of $26 billion against exports of $11.4 billion.
Remittances, which rise every year, are also seen as being used mainly to plug the trade gap rather than put to better use, with neither the government nor the central bank having devised a policy to deploy them more productively.
The reserves milestone follows Saudi Arabia’s decision to roll over its $3 billion deposit with Pakistan once again.